Could We Soon See Some Relief With Capital Gains Taxes?
Every week I talk to longtime Mooresville and Lake Norman homeowners who are thinking about downsizing, moving closer to the grandkids, or finally cashing in on the lake house. Once we start running the numbers, many are surprised to learn that a big piece of their profit could go to the IRS.
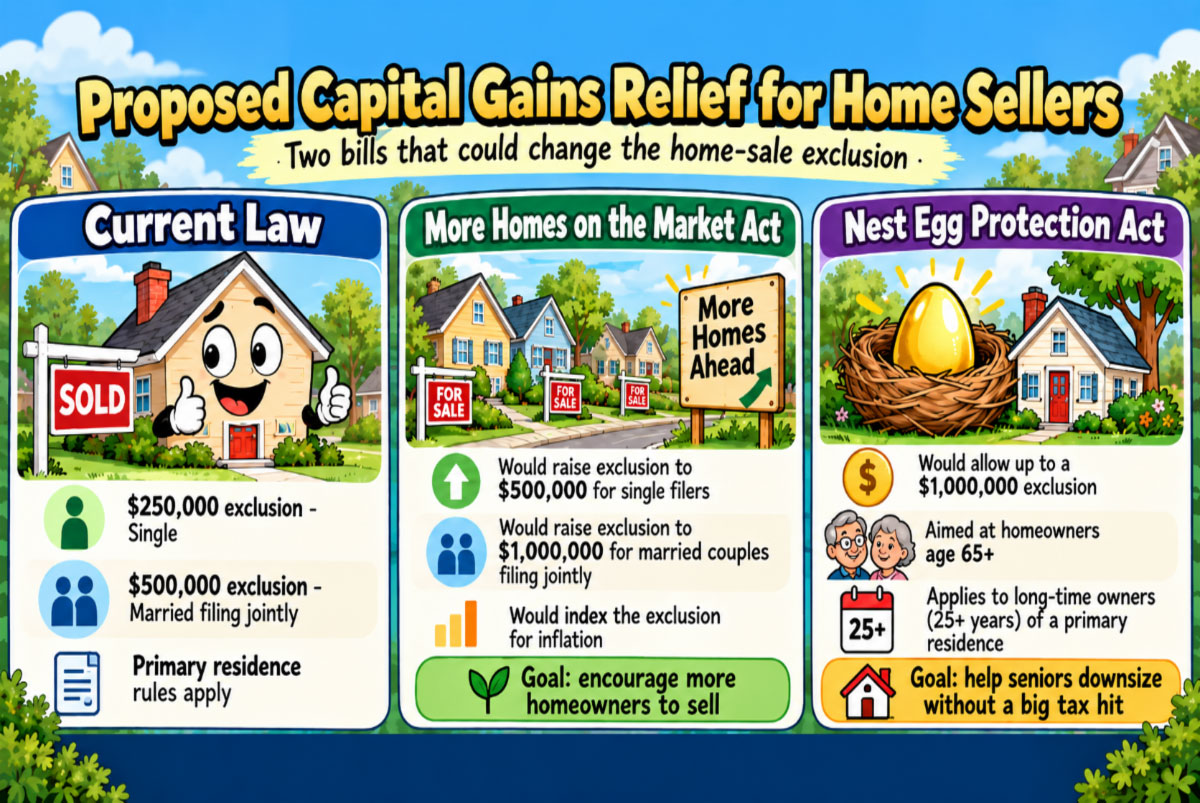
Here’s how it works. When you sell your primary residence, federal law lets you exclude up to $250,000 of profit from capital gains tax if you’re single, or $500,000 if you’re married filing jointly. To qualify, you need to have owned the home and lived in it as your main residence for at least two of the last five years. For most sellers, that’s plenty, and they never pay a dime.
The catch is that those limits were set in 1997 and have never been adjusted. Back then, $500,000 of profit on a house was almost unheard of. Adjusted for inflation, the $500,000 limit would be worth about $1 million today. Home values have kept rising, but the exclusion hasn’t moved.
Say a married couple bought a waterfront home on Lake Norman in 2000 for $350,000 and put $150,000 into it over the years: a new dock, a remodeled kitchen, a screened porch. Today it sells for $1.4 million. Their profit, before selling costs, is about $900,000. After their $500,000 exclusion, roughly $400,000 is taxable. At the 15% federal rate, that’s a $60,000 tax bill before North Carolina takes its share.
That’s the situation for many of our longtime residents. According to the National Association of Realtors, about 29 million homeowners, roughly one in three, could already owe capital gains tax if they sold today. NAR projects that number will grow to about 70% of homeowners by 2035.
It also explains a lot about today’s market. Many empty nesters are staying in homes they’d otherwise sell because the tax bill makes moving feel like a penalty. When they stay put, fewer homes come on the market, and younger families have fewer options.
Congress May Do Something Useful For Once – (Hopefully) – Two proposals in Washington would change this.
The First: More Homes on the Market Act (H.R. 1340),
It would double the exclusion to $500,000 for single filers and $1 million for married couples, then index it to inflation so it doesn’t fall behind again. It has serious support, with more than 150 House cosponsors and a Senate companion bill with 23 cosponsors as of August.
The second is the: Nest Egg Protection Act (H.R. 9064)
This one is aimed at seniors. Homeowners 65 and older who have owned their primary residence for at least 25 years could exclude up to $1 million in profit, whether single or married. It’s temporary: as written, it would apply to sales in tax years 2027 through 2030.Under either bill, the couple in my example would owe nothing on their $900,000 gain. That’s a $60,000 difference.
What Doesn’t Count?
Not every dollar you’ve spent on your home counts toward those improvements. A new roof, an addition, or a remodeled bathroom counts. Painting the living room, fixing a leaky faucet, or replacing a broken window generally doesn’t. The IRS treats those as repairs, not improvements. If you’ve been tossing your receipts, this might be the article that changes that habit.
So what do you think? Should Congress raise the limits, and would a change like this get you to sell sooner? I’d love to hear your thoughts.
Share this on social media:
Could We Soon See Some Relief With Capital Gains Taxes?
Every week I talk to longtime Mooresville and Lake Norman homeowners who are thinking about downsizing, moving closer to the grandkids, or finally cashing in on the lake house. Once we start running the numbers, many are surprised to learn that a big piece of their profit could go to the IRS.
Here’s how it works. When you sell your primary residence, federal law lets you exclude up to $250,000 of profit from capital gains tax if you’re single, or $500,000 if you’re married filing jointly. To qualify, you need to have owned the home and lived in it as your main residence for at least two of the last five years. For most sellers, that’s plenty, and they never pay a dime.
The catch is that those limits were set in 1997 and have never been adjusted. Back then, $500,000 of profit on a house was almost unheard of. Adjusted for inflation, the $500,000 limit would be worth about $1 million today. Home values have kept rising, but the exclusion hasn’t moved.
Say a married couple bought a waterfront home on Lake Norman in 2000 for $350,000 and put $150,000 into it over the years: a new dock, a remodeled kitchen, a screened porch. Today it sells for $1.4 million. Their profit, before selling costs, is about $900,000. After their $500,000 exclusion, roughly $400,000 is taxable. At the 15% federal rate, that’s a $60,000 tax bill before North Carolina takes its share.
That’s the situation for many of our longtime residents. According to the National Association of Realtors, about 29 million homeowners, roughly one in three, could already owe capital gains tax if they sold today. NAR projects that number will grow to about 70% of homeowners by 2035.
It also explains a lot about today’s market. Many empty nesters are staying in homes they’d otherwise sell because the tax bill makes moving feel like a penalty. When they stay put, fewer homes come on the market, and younger families have fewer options.
Congress May Do Something Useful For Once – (Hopefully) – Two proposals in Washington would change this.
The First: More Homes on the Market Act (H.R. 1340),
It would double the exclusion to $500,000 for single filers and $1 million for married couples, then index it to inflation so it doesn’t fall behind again. It has serious support, with more than 150 House cosponsors and a Senate companion bill with 23 cosponsors as of August.
The second is the: Nest Egg Protection Act (H.R. 9064)
This one is aimed at seniors. Homeowners 65 and older who have owned their primary residence for at least 25 years could exclude up to $1 million in profit, whether single or married. It’s temporary: as written, it would apply to sales in tax years 2027 through 2030.Under either bill, the couple in my example would owe nothing on their $900,000 gain. That’s a $60,000 difference.
What Doesn’t Count?
Not every dollar you’ve spent on your home counts toward those improvements. A new roof, an addition, or a remodeled bathroom counts. Painting the living room, fixing a leaky faucet, or replacing a broken window generally doesn’t. The IRS treats those as repairs, not improvements. If you’ve been tossing your receipts, this might be the article that changes that habit.
So what do you think? Should Congress raise the limits, and would a change like this get you to sell sooner? I’d love to hear your thoughts.